Construction & Contractors
Construction & Heavy Equipment Financing in Canada
Finance new or used construction equipment through one application with access to 40+ financing sources. From a single mini excavator to a full earthmoving spread, Raymond Leigh structures heavy equipment transactions across Canada from about $50,000 to $5 million.
At a Glance
Construction Equipment Financing in Canada: At a Glance
What can be financed
Excavators, loaders, skid steers, dozers, graders, cranes, lifts, paving and concrete equipment, plus the trucks and trailers that move them.
Transaction size
About $50,000 to $5 million, from one compact machine to a multi-unit fleet.
Used equipment
Used machines may be considered based on age, hours, condition and value. Hour meter readings and inspection reports help.
Private sales and auctions
Private and auction purchases may be considered when the machine can be inspected, valued and transferred free of liens.
Seasonal cash flow
Some financing sources offer payment schedules that follow a contractor's building season, reviewed file by file.
Machines you already own
Equity in paid-down iron may support equipment refinancing or a sale-leaseback.
Construction & Contractors
Financing Built Around Construction Businesses
Contractors win work with equipment. The right excavator or loader decides which jobs you can bid, how fast you finish and how many people you need on site. It is also usually the largest purchase a construction business makes.
Cash is the constraint. Holdbacks, progress billing and slow-paying general contractors mean money often arrives weeks or months after the work is done. Paying cash for a machine drains the same account that covers payroll, fuel and materials between draws.
That is why most contractors finance. New machines carry warranties and predictable maintenance. Used machines cost less up front and are easy to find through dealers, auctions and other contractors. Both can be financed, and the structure can be built around the season you work in.
Equipment
Construction Equipment We Finance
From earthmoving to finishing work, these are the categories construction businesses finance.
Earthmoving
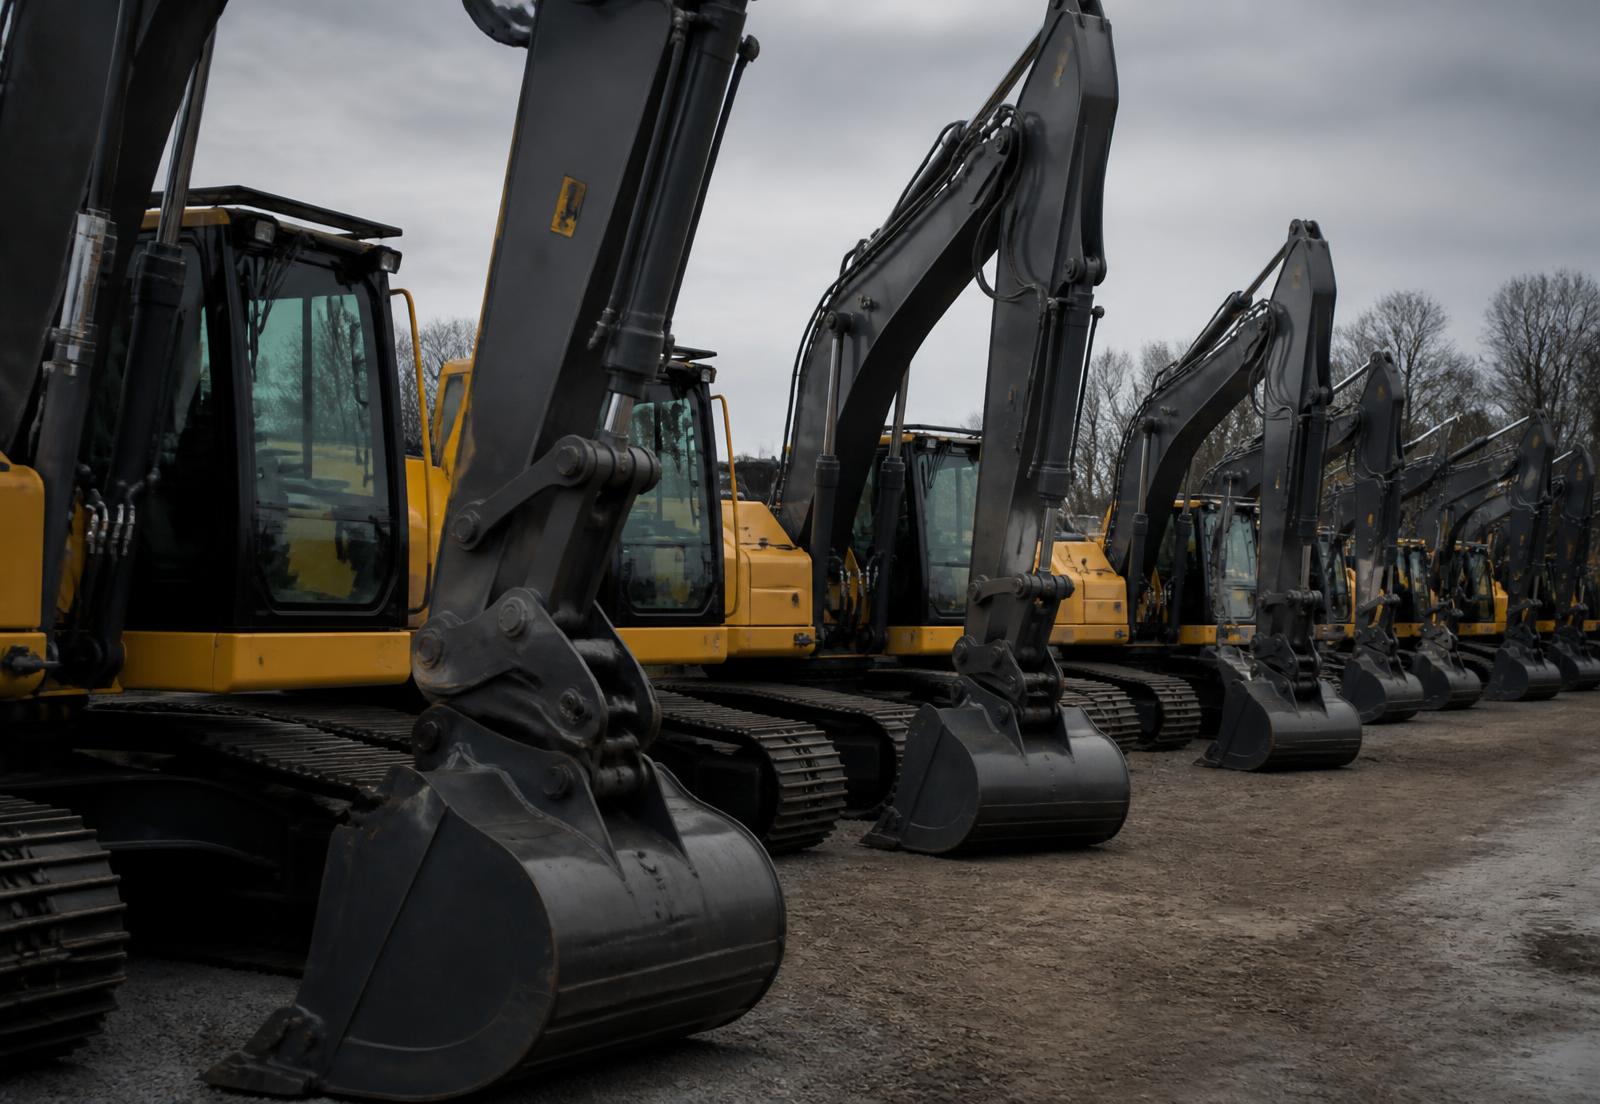
Excavators, mini excavators, bulldozers, wheel loaders and motor graders.
Compact equipment
Skid steers, compact track loaders, mini excavators, backhoes and attachments.
Lifting and access
Cranes, telehandlers, boom lifts and scissor lifts.
Road and paving
Pavers, compactors, rollers, milling machines and trenchers.
Concrete equipment
Concrete pumps, mixers, saws and finishing equipment.
Trucks and trailers
Dump trucks, service trucks, float trailers and equipment trailers.
By Machine
Heavy Equipment Financing by Machine Type
Financing sources look at each machine class differently. Resale demand, hours and how the machine is used all affect the structure.
Excavator Financing
Excavators are among the most commonly financed machines in construction because they hold value and resell well. Mini excavators, mid-size and large excavators can all be financed new or used. Hours, undercarriage condition and the attachments included are part of the review.
Skid Steer & Compact Equipment Financing
Skid steers, compact track loaders and mini excavators are a contractor's workhorses. They are often financed as a package with buckets, forks, augers and other attachments, so one transaction covers the whole setup.
Loader & Backhoe Financing
Wheel loaders and backhoe loaders are financed for site work, aggregate handling, utility jobs and snow removal. Snow contractors may ask about payment schedules that match winter revenue.
Dozer & Grader Financing
Bulldozers and motor graders support earthmoving, road building and site preparation. Larger units with GPS grade control often have higher price tags, and financing sources will review the contractor's backlog and experience with that class of machine.
Crane Financing
Crane financing covers rough-terrain, all-terrain and boom truck cranes. These are specialized assets, so financing sources pay close attention to the operator's track record, inspection certifications and contracted work.
Used Construction Equipment Financing
Yes, used construction equipment can often be financed in Canada, subject to the machine's age, hours, condition, price and the borrower's profile. Machines bought from dealers are the simplest. Private and auction purchases need more documentation. See used equipment financing options.
Construction Fleet Financing
Contractors adding several machines for a large contract can finance them together instead of one by one. A fleet transaction can include excavators, loaders, trucks and trailers in a single structure.
Heavy Equipment Refinance
Contractors who own machines outright can use heavy equipment refinancing or a sale-leaseback to free up cash for a bond, a new contract or a gap in progress payments.
Financing Options
Financing Options for Construction Businesses
Different jobs call for different structures. These are the ones contractors use most, but each depends on the machine and the business.
Equipment Financing
Finance the purchase of a new or used machine. The equipment is the main security, which keeps other credit lines free.
Explore equipment financingEquipment Leasing
Leasing can lower payments and make upgrades easier at the end of the term. Terms vary by source.
Seasonal Payment Structures
Some financing sources can schedule lower payments in the off-season. This is reviewed case by case.
Multi-Asset Financing
Bundle machines, attachments, trucks and trailers into one transaction.
Equipment Refinance
Use equity in machines you already own to raise working capital.
Explore equipment refinanceSale-Leaseback
Sell owned machines to a financing source and lease them back. The iron stays on the job site and the cash goes to the business.
Explore sale-leasebackFor gaps between progress draws, some contractors also look at invoice factoring on approved invoices.
Use Cases
Common Construction Financing Scenarios
Buying the first big machine
A landscaping or small excavation business stops renting and buys its first mini excavator or compact track loader so it can take on larger jobs.
Gearing up for a contract
A civil contractor wins a municipal project and needs another excavator, a loader and two dump trucks before mobilization.
Replacing worn-out iron
A concrete contractor trades in a high-hour machine whose repair bills now exceed what a payment on a newer unit would cost.
Buying at auction
An earthmoving contractor finds a late-model dozer at auction and arranges financing ahead of the sale date.
Freeing cash tied up in equipment
A road builder with a paid-off fleet uses a sale-leaseback to cover holdbacks while waiting for final payment.
Ontario & Quebec
Ontario and Quebec Notes for Contractors
These details come up regularly in Ontario and Quebec construction deals. They are general pointers; your lawyer and accountant have the final word.
Holdbacks and cash flow
Holdbacks are standard on many Ontario and Quebec construction contracts. Financing sources understand this, and a contract schedule helps explain the timing of your receivables.
Lien searches on used machines
Used equipment is checked for existing liens through the PPSA registry in Ontario or the RDPRM in Quebec, especially on private and auction purchases.
Seasonal work
Frost, road restrictions and winter shutdowns affect revenue in both provinces. Ask whether seasonal payments are available for your machine and file.
For equipment dealers
How Construction Equipment Dealers Can Offer Customer Financing
Construction equipment dealers can offer customer financing by partnering with Raymond Leigh. Your sales team introduces the buyer, and we take the deal to financing sources that fit the machine, the contractor and the structure. You do not need an in-house finance department or your own lending capital.
Contractors think in monthly payments and seasons, not sticker prices. A dealer financing program lets your team quote a payment on an excavator or a loader package and keep the deal moving. It also gives you options when a contractor's bank is slow or declines, which happens often with used machines, newer businesses and seasonal operators.
Financing can cover new and used inventory, attachments, and multi-machine orders. You stay in control of the sale. We manage applications, lender routing and documents, and keep you updated on status so you can plan delivery.
How can heavy equipment dealers offer financing?
By working with a financing partner that connects your buyers to multiple financing sources. Raymond Leigh coordinates the process while you keep the customer relationship.
Can customers apply while buying from us?
Yes. Buyers can start an application during the sales process with the quote and machine details. That keeps the financing tied to the deal instead of a separate trip to the bank.
Can used inventory and rental fleet machines be financed?
Often, yes. Used and ex-rental machines are reviewed on hours, condition and price, the same way as any used equipment purchase.
Why Raymond Leigh
One Financing Process. More Places to Take the Deal.
Banks and captive finance companies each work within one set of rules. A used machine, a young company or a seasonal cash cycle can fall outside them. Raymond Leigh brings one application to 40+ financing sources so the deal can be matched with a source whose criteria fit.
- Excavators, loaders, cranes, compact equipment and trucks
- New, used, dealer, private and auction purchases where appropriate
- Single machines and fleet packages, about $50K to $5M
- Refinancing and sale-leaseback on owned equipment
- Seasonal structures where a financing source offers them
- One contact from application to funding
How It Works
How Construction Equipment Financing Works
Applying does not commit you to anything, and approval is never guaranteed. Here is what happens after you reach out.
Tell Us About the Equipment
Share the machine, quote or listing, plus basic details about your company and work.
We Review the Transaction
We review the contractor, the equipment and the amount you need financed.
We Identify Financing Options
Your file goes to financing sources suited to the machine type, the business and the structure.
Complete the Transaction
When documents and conditions are in place, funding is coordinated with the dealer, auction or seller.
FAQ
Construction & Contractors Financing Questions
Yes. Used construction equipment is commonly financed, subject to the machine's age, hours, condition and price and the borrower's profile. Inspection reports and hour meter photos make the review easier.
There is no single cut-off. Each financing source sets its own limits on age and hours. Older machines may still be financed but often with shorter terms or a larger down payment.
Yes. Attachments such as buckets, augers, breakers and forks can usually be included in the same transaction as the machine.
Sometimes. Newer contractors are reviewed more on personal credit, industry experience, contracts and down payment. Terms may be more conservative than for an established company.
Some financing sources offer seasonal or skip-payment schedules. It depends on the source, the equipment and the business, so it is reviewed on each file.
Yes, potentially. Equipment refinancing and sale-leasebacks let contractors borrow against machines they own while continuing to use them.
Yes. The dealer refers the customer and Raymond Leigh coordinates financing through third-party sources. The dealer does not take on credit risk or carry the loan.
It can. Ex-rental and used inventory is reviewed on hours, condition and price like any used machine.
Next Step
Put the Next Machine to Work
Send us the quote or listing. We will review the machine and your business and tell you what options look realistic.